Mobile Financial Services (MFS) is fairly active in Bangladesh but the cost of transactions and the level of literacy of the ultimate beneficiaries, namely the unbanked population, are major impediments to financially including them. The density of mobile service coverage across the country makes MFS a good solution for money transfer to the last mile.
The success of mobile financial services platform has been phenomenal but somewhat limited in scope as the main focus has been on fund transfer. This has facilitated mainly remittance distribution and to a lesser extent, trading. According to Bangladesh Bank, as on March 2017, there were 50.4 million registered clients but only 24.6 million were active users.
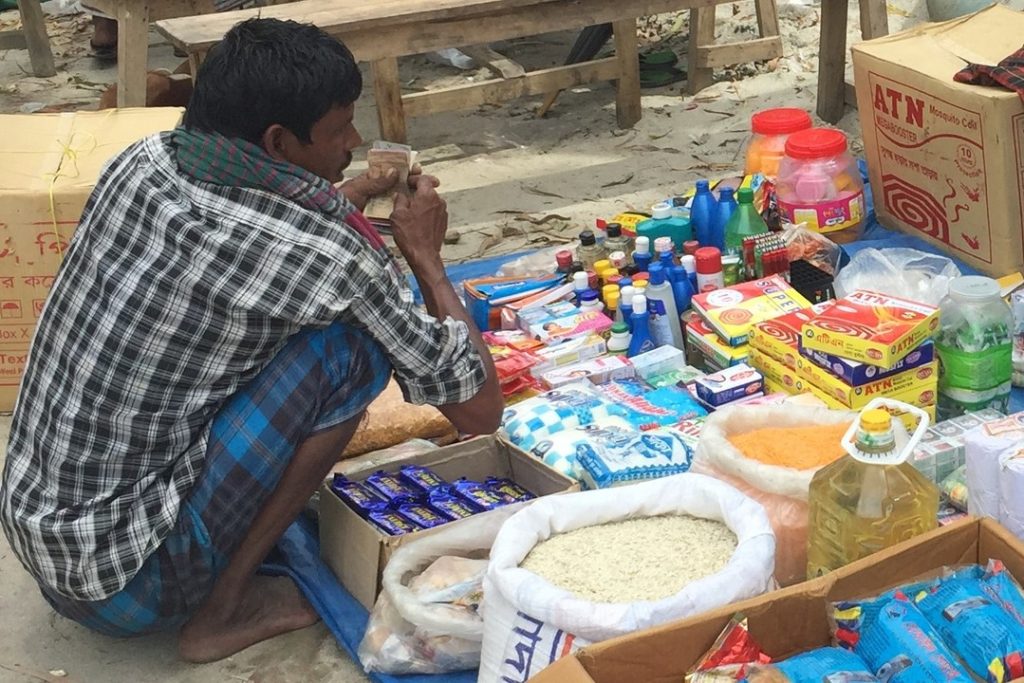
Financial literacy is very important but needs to include awareness of financial risks that no longer need to be taken for granted. An individual in a remote location in Bangladesh, whom I had met on an assignment, proudly stated that he kept his money in a wooden lock-box rather than a mobile banking account. He went on to share an incident where a rat had gotten into the lock-box and eaten some of the cash. He still considered it cheaper than the cost of cashing in and out of a mobile banking account.
This really drove home to me what needs to be done for greater financial inclusion. This also highlighted the fact that the cost of using mobile banking services are considered expensive for regular use even though other means of conducting the transactions such as visiting a bank branch, the risk associated with non-regulated services such as courier services, etc. can be even more expensive and often risky with respect to carrying cash long distances.
At present not only do individuals with low literacy levels face difficulty in making transfers after opening an MFS account, without significant hand-holding in learning to use a MFS system on their mobile phones, they need to open multiple accounts because they cannot transfer funds across providers.
This means that in addition to the obstacle of learning to use multiple systems, they also need to maintain funds as balance in each of those accounts to transact virtually on a regular basis and in particular for business and/or commerce. Then there is additional hassle if one account does not have sufficient funds for the transaction.
Increased competition may be the only way to reduce the charges and this can happen quicker if interoperability is mandated among MFS providers. This will reduce some of the competitive advantage of the market leaders and open the door for more players but would probably result in greater transaction volume for all players.
Interoperability would be more effective in reducing the customers’ dependence on cash-based transactions but enabling them to send and receive funds for all kinds of goods and services through their phones more efficiently and at significantly lower costs than presently possible. MFS needs pump up their transactions volume to be successful. The sooner this can be achieved the sooner the MFS ecosystem in Bangladesh can deepen.